
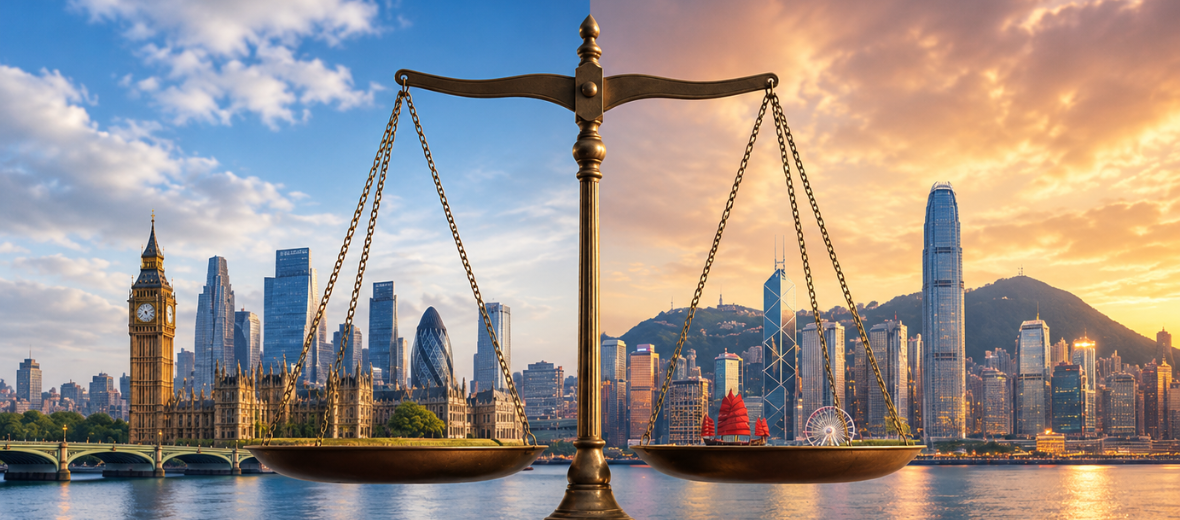
Awareness of diversification and investing internationally seems to be more common these days. So is this the home bias label one that’s had its day?
For years, one of the most common pieces of investment advice has been: don’t over-concentrate in your home market. Spread your risk internationally, the thinking goes, or you’re exposed to a single economy’s fortunes. Home bias investing has been treated as a blind spot to correct for decades, and it’s rarely questioned.
But is that still fair? Estimates suggest around 70% of FTSE 100 companies’ revenue comes from abroad, with analysts at FTSE Russell putting the figure closer to three-quarters. If that’s right, a portfolio built from FTSE 100 names may already look far more international than the “UK” label on the index suggests. Which raises the question of whether that concern still applies to a market like this one.
A familiar name, seen differently
For Charlton House Wealth Management’s Hong Kong-based clients, this isn’t an abstract statistic; it’s visible in a company most will know well. HSBC, one of the largest constituents of the FTSE 100, generated $71.0bn in group revenue in 2025, with its Hong Kong business alone contributing $15.9bn, up 6% on a constant currency basis. It’s a UK-listed company, reporting in US dollars, doing much of its business in a currency pegged to the dollar, in a market thousands of miles from London.
Where do you sit: does that still count as a “home” holding for a UK-based investor, or has the label stopped meaning very much?
The case that it no longer matters
Plenty of investors would say home bias investing is a solved problem, and their argument is straightforward: what matters for diversification is where a business actually earns its money, not where its shares happen to be listed. On this view, a UK-listed, globally-earning company already gives an investor real exposure to US, Asian and European growth – without the extra dealing costs or tax complexity of buying shares directly in those markets.
Picture an investor who spent the last decade deliberately avoiding “home bias”, tilting away from UK large caps and buying US and Asian holdings directly instead, at extra cost and complexity. If FTSE 100 companies were already earning those same profits, in those same currencies, that investor may have paid a premium for exposure they could have held for less. If that’s true, worrying about it today means fighting a war a company’s own strategy had already settled for them.
The case that it still does
Others would push back hard on that. The currency-hedging argument for holding UK assets hasn’t disappeared – it’s just narrower than it used to be. In a balanced portfolio with a meaningful weight in UK government and corporate bonds, sterling-denominated assets can still provide stability for investors who will ultimately spend in sterling. For that kind of 60/40-style portfolio, home bias investing arguably still earns its place.
This logic breaks down in equity-heavy portfolios. A share listed on the London Stock Exchange in sterling, earning most of its profit in US dollars or Hong Kong dollars, doesn’t behave like a sterling asset when currencies move – it behaves like the currency it actually earns in.
Being UK-listed and being sterling-exposed are two different things. A company earning mostly in dollars gives you dollar exposure, not the sterling ballast some investors assume comes with a UK listing. For a sterling investor, that cuts both ways: a weaker pound makes those profits worth more in sterling terms, while a stronger pound makes them worth less.
A counter-argument worth holding in mind
Here’s something that complicates both sides: even when UK-listed companies deliver real international revenue exposure, the UK market as a whole remains fairly narrow sector-wise. It’s light on the technology names that have driven much of global equity growth over the past decade, and heavier in financials, energy and consumer staples. So a portfolio built around UK-listed shares might capture international earnings without capturing the sectors that have grown the most.
Where home bias still shows up
Home bias investing used to be standard in UK pensions. In the mid-1990s, most of a typical scheme’s equities were UK shares, and pensions have only moved towards global portfolios since. In Hong Kong, it’s still common in MPFs, where so-called “global” equity funds can carry a heavy over-allocation to Hang Seng stocks, so it’s worth checking what’s under the bonnet.
Where do you land?
So, is home bias investing still a risk worth managing, or a rule of thumb that’s outlived its usefulness? We suspect the honest answer depends on what kind of portfolio you’re looking at, and how closely “listed here” actually maps to “earns here” for the businesses you hold. Three separate things – where a business earns its revenue, what currencies it’s exposed to, and which sectors it gives access to – don’t always move together, and neither a listing location nor a fund’s name will tell you much about any of them.
We’d be curious where you sit on this. If it’s a conversation worth having about your own portfolio, we’re always happy to talk it through.
📩 Email us anytime: info@charltonhousewm.co.uk
📞 UK: +44 (0) 208 0044900
📞 Hong Kong: +852 3903 9004
 Production